Order your debts by interest rate, highest first, and pay the least interest possible.
The debt avalanche is the method the math likes best. Pay the minimum on everything, put every extra dollar on the debt with the highest interest rate, and when it is gone move the whole payment to the next highest rate. Because the most expensive debt goes first, you pay less interest overall than with any other order.
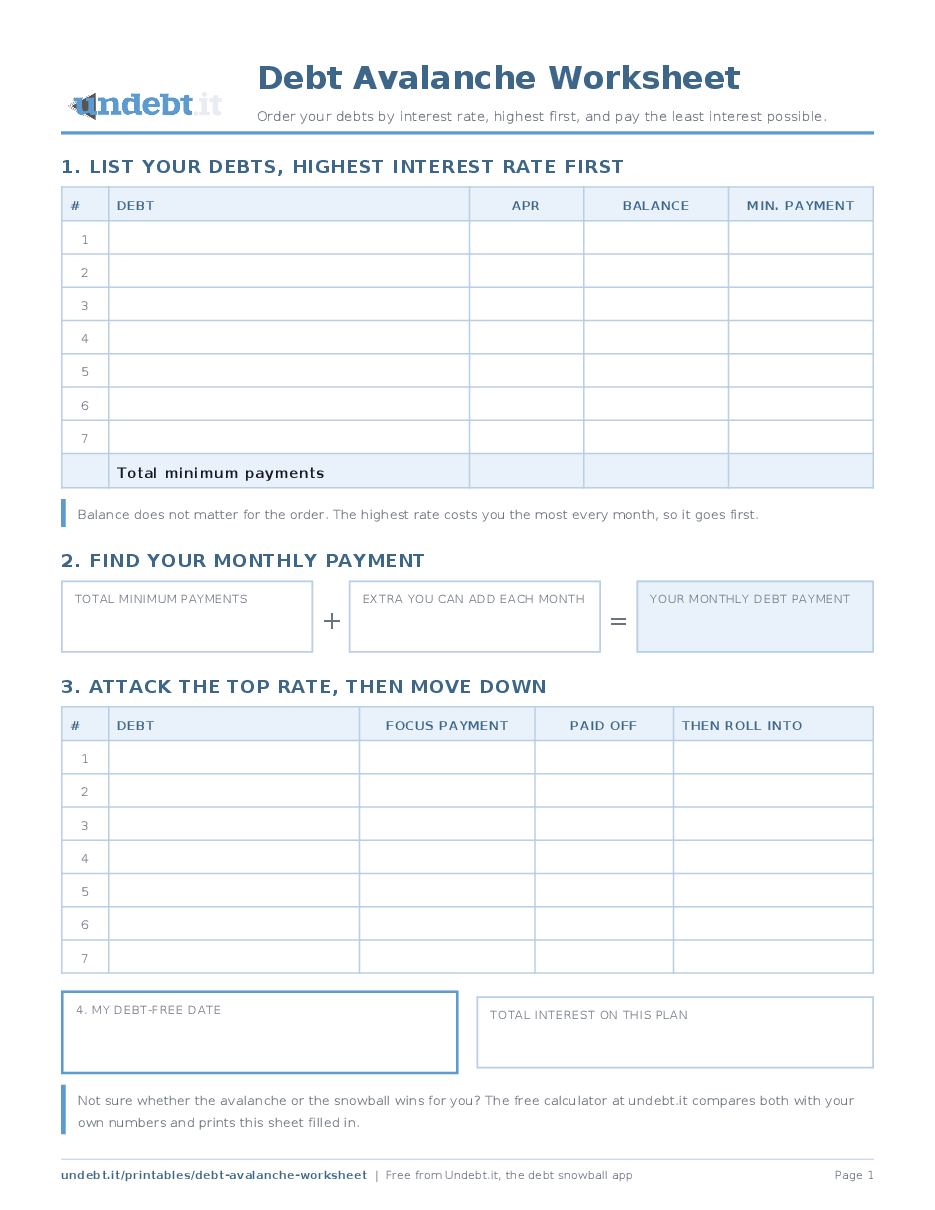
This worksheet is the avalanche twin of the snowball worksheet: list the debts by APR, add your minimums to the extra you can commit, roll the payment down the list and name your debt-free date. The steps are the same; only the order changes.
The avalanche asks for patience, because the highest-rate debt is often also a large one and the first payoff can be months away. If you know you need an early win to keep going, the snowball is the better fit. The snowball vs avalanche calculator shows exactly how much interest each order costs with your own debts.
Download the free PDF
Free, no signup, no email address. Pick your paper size; every version is one page and prints on any home printer.
The ink saver version is the same sheet in black and gray for cheap printing. Print at 100 percent, not "fit to page", so the rows stay a comfortable height for handwriting.
Rather have the numbers filled in for you? Undebt.it tracks all of this online for free, and personalized versions of these printables, built from your own plan, are on the way.
How to use it
- Step 1: list by rate, highest first. Write the APR from each statement. Balance does not affect the order.
- Step 2: find your monthly payment. Total minimums plus the extra you can commit. Keep that number fixed month to month.
- Step 3: attack the top rate. It gets your payment minus the minimums still owed below it. When it clears, its share moves to the next rate down.
- Step 4: name the date and write it on the sheet. Tape the sheet somewhere you pay bills.
Tips that make it stick
- Promotional 0% balances go to the bottom of the list, but write the date the promotion ends beside them and move them up before it does.
- If a lower-rate debt is tiny, clear it first anyway. Losing a minimum payment frees cash and the interest cost of the detour is pennies.
- Re-check the rates twice a year. Card rates move, and a rate change can reorder the list.