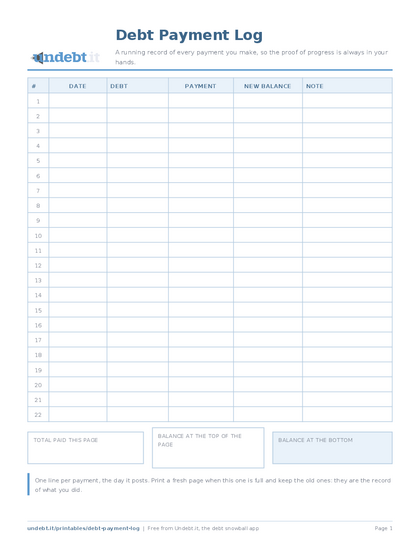
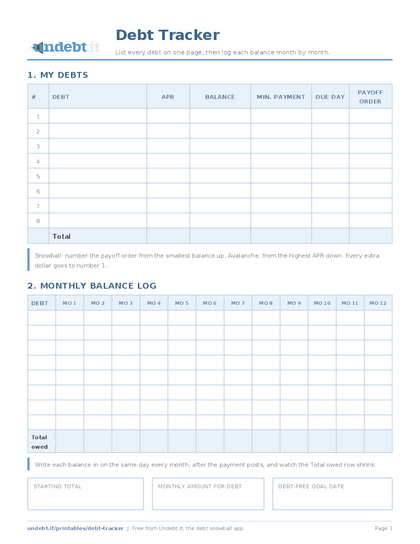
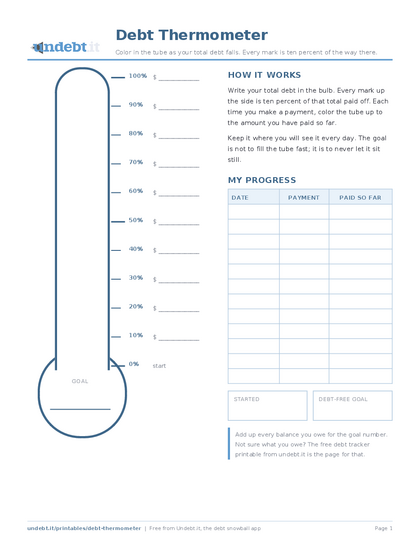
For one loan: car, student or mortgage. Log each payment and shade the bar as the balance drops.
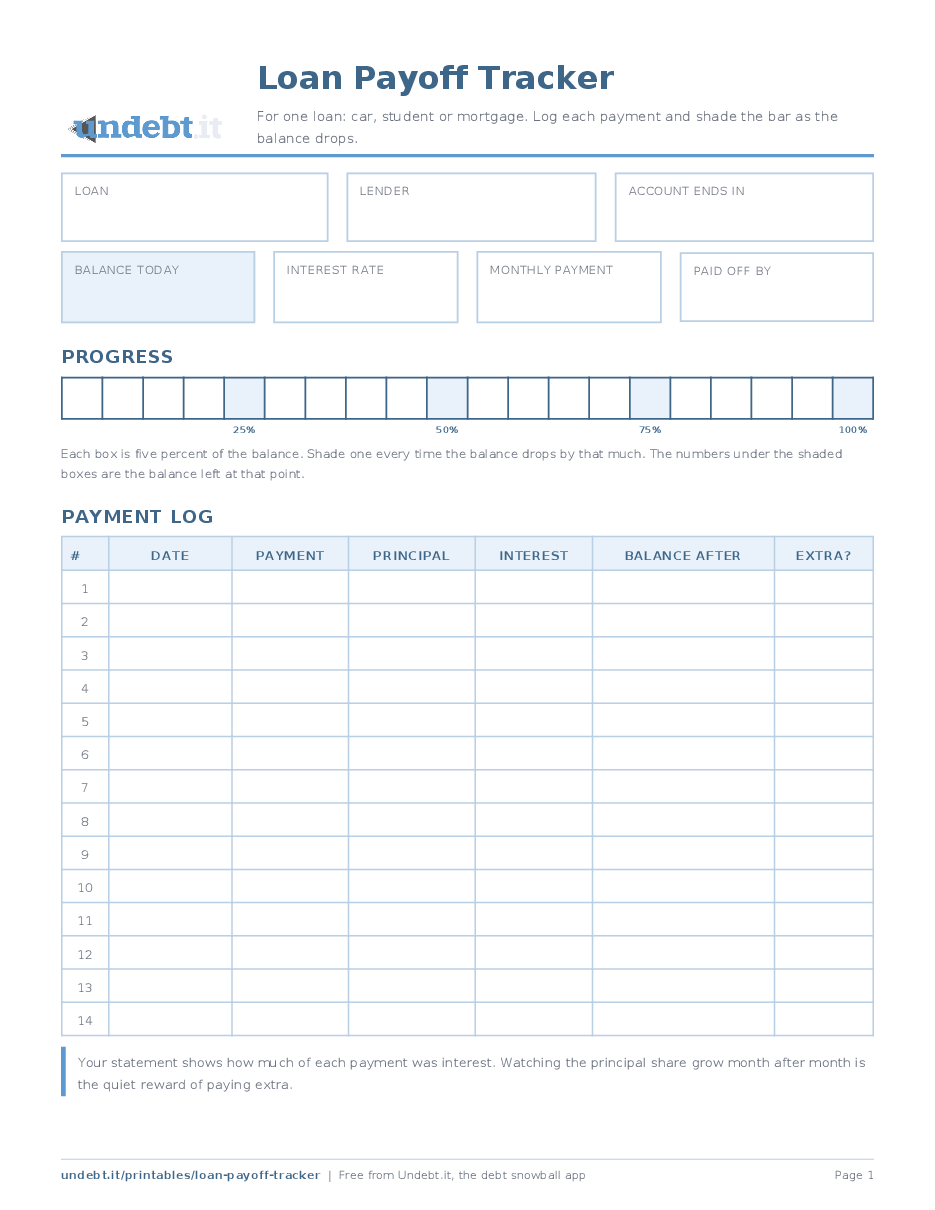
Installment loans are different from cards. The payment is fixed, the end date is known, and the only real question is whether you will pay extra and get there sooner. This tracker is built for one loan at a time: a car loan, a student loan, a personal loan or a mortgage. Loan details across the top, a twenty-box progress bar in the middle and a payment log below.
The log has columns for principal and interest, because a loan statement splits every payment into the two and watching the split change is the quiet reward of paying extra. Early on, most of each payment is interest. Every extra dollar goes entirely to principal, and from then on every regular payment carries a little less interest than it would have.
The progress bar has twenty boxes, five percent each, with the quarter marks shaded. Shade a box each time the balance drops by five percent of where you started. On a mortgage that box might take a year; on a car loan a few months. Either way it is the picture of the loan getting smaller, which the statement never quite gives you.
Download the free PDF
Free, no signup, no email address. Pick your paper size; every version is one page and prints on any home printer.
The ink saver version is the same sheet in black and gray for cheap printing. Print at 100 percent, not "fit to page", so the rows stay a comfortable height for handwriting.
Rather have the numbers filled in for you? Undebt.it tracks all of this online for free, and personalized versions of these printables, built from your own plan, are on the way.
How to use it
- Fill in the loan details from the statement: balance today, interest rate, monthly payment and the payoff date at the current pace. Lender and the last digits of the account are handy when you call them.
- Divide the balance by 20. That is one box on the progress bar. Write the balance at each shaded mark underneath if you like a target to aim at.
- Log each payment with its principal and interest split from the statement, the balance after, and a tick in the Extra column if you paid more than the required amount.
- Shade a box every time the balance falls by another five percent of the starting balance.
Tips that make it stick
- Tell the lender an extra payment is to go to principal, and check the next statement that it did. Some apply it to next month's payment instead, which saves you nothing.
- Round the payment up to the next round number and pay that every month. A $215 car payment paid as $250 clears months early and you stop noticing the difference within a year.
- One tracker per loan. If you have two, print two; the bar only makes sense for a single balance.